If you own a short-term rental and you materially participate in it, the STR loophole can let its loss offset your W-2 income instead of sitting stuck as a passive deduction. How much that is actually worth depends on your purchase price, how much of it a cost segregation study can move into short-lived property, your tax bracket, and whether you can prove material participation. The free STR tax savings calculator runs your own numbers on the real 2025 and 2026 brackets, so you are not guessing at a flat percentage.
This post walks through how the loophole works, a worked example using the calculator’s own default numbers, what changes the result, and where the savings disappear if you cannot back them up. For the fundamentals, start with the STR loophole guide.
How the STR loophole turns depreciation into tax savings
A short-term rental whose average guest stay is 7 days or less is not a “rental activity” under the passive loss rules (Treas. Reg. 1.469-1T(e)(3)(ii)(A)). That single fact is the whole loophole: if you materially participate in the activity, its loss is non-passive, and a non-passive loss can offset your W-2 and other income the same year it happens, instead of waiting for passive income or a sale.
Depreciation is what creates the loss to offset in the first place. A cost segregation study splits the purchase price into 5-year personal property (appliances, carpet, furnishings), 15-year land improvements (driveway, landscaping, fencing, pool) and the building itself. Bonus depreciation then lets you deduct all of the 5- and 15-year property, and any furniture bought separately, in the very first year: 100% for property acquired after January 19, 2025, or 40% (2025) and 20% (2026) for an earlier binding contract. The building is depreciated over 39 years with the mid-month convention, because a house rented to transient guests is usually nonresidential real property, not the 27.5-year residential kind. Using 27.5 years anyway is a common mistake in STR tax math, and it overstates the building’s yearly depreciation by about 42%.
Material participation is the other half. Without it, the loss is passive no matter how much depreciation you generate, and the calculator will show you exactly that: $0 in savings. The tests that count are covered on the material participation tests page: more than 100 hours and at least as much as anyone else, more than 500 hours, or one of the other Treasury Regulation 1.469-5T(a) tests.
A worked example: $500,000, 30% cost segregation reclass
The calculator opens with a realistic default scenario, which is a useful baseline before you plug in your own numbers. A married couple earning $300,000 in W-2 and other income buys a $500,000 short-term rental (20% land value), adds $20,000 of furniture bought separately, places it in service in June 2026, materially participates with an average guest stay of 7 days or less, and orders a cost segregation study that reclassifies 20% of the building to 5-year property and 10% to 15-year land improvements.
| Step | Amount |
|---|---|
| Depreciable basis (price minus land, plus furniture) | $420,000 |
| Bonus depreciation (100% of 5-, 15-year property and furniture) | $140,000 |
| Building, 39-year, first year (mid-month) | $3,895 |
| First-year depreciation | $143,895 |
| STR loss (after $10,000 of operating income) | $133,895 |
| Federal tax savings | $30,585 |
| State tax savings (5% rate assumed) | $6,695 |
| Total first-year savings | $37,280 |
Without a cost segregation study, the same property still gets its building depreciation and 100% bonus on the furniture bought separately, but the savings drop to $4,513. The study is most of the number.
What changes the result
A few things move the outcome more than most owners expect:
- Acquisition date, not placed-in-service date. 100% bonus depreciation only applies to property acquired after January 19, 2025. “Acquired” usually means the day you closed; an earlier signed contract counts only if it was binding, and losing an earnest-money deposit under 5% of the price does not make it binding. An earlier binding contract gets 40% in 2025 or 20% in 2026 instead.
- Real tax brackets, not one flat rate. A large loss pushes you down through several brackets, so each additional dollar of loss saves less than the one before it. A flat-percentage rule of thumb overstates the savings when a large loss drops you into lower brackets.
- The excess business loss limit, IRC 461(l). This caps how much of the loss can offset your W-2 and other income in one year: $256,000 single and $512,000 married filing jointly for 2026. Anything above the cap carries forward instead of vanishing.
- Material participation, or the savings are $0 this year. Without it, the loss is passive and suspended until you have passive income or sell.
- State conformity. Several states, including California, do not allow bonus depreciation, so the state half of the savings can be much smaller than the calculator’s upper-bound estimate.
- Recapture when you sell. Depreciation you took gets taxed back: ordinary rates on the 5-year property and furniture, and on 15-year bonus depreciation above straight line, and up to 25% on the building. A 1031 exchange defers it; the calculator does not model a sale.
Already own a rental for years, or it is a long-term rental instead of an STR? The cost segregation calculator covers real estate professional status, the $25,000 passive loss allowance, and the Form 3115 catch-up for property already in service.
Prove material participation, or the savings disappear
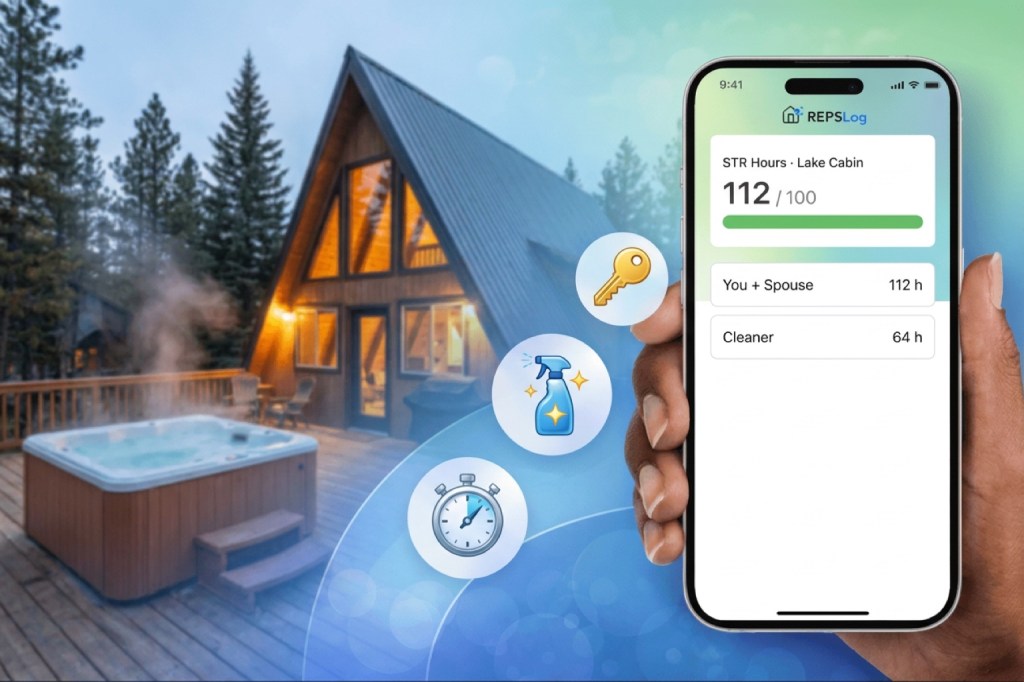
Every number above depends on one fact the calculator cannot verify: that you actually put in the hours. The Tax Court does not accept an after-the-fact “ballpark guesstimate” of hours. In Moss v. Commissioner, 135 T.C. 365 (2010), a real estate professional case, the taxpayer’s summary of hours, written two years later, fell short of the 750-hour test. The same standard applies to the STR loophole’s 100-hour and 500-hour tests, and to the “nobody else participated more than you” condition of the 100-hour test: you need your cleaner’s, co-host’s and property manager’s hours on the record too, not just your own.
REPSLog is built for exactly this. Log hours by voice or timer as the work happens, attach receipts and photos to each entry, log a spouse’s or contractor’s hours as a separate participant so the comparison holds up, and export a CPA-ready PDF, Excel or CSV report at year end. It is free to start, on iPhone, Android and the web.
When to talk to your CPA
Run the calculator with your own purchase price, your own land value (your county assessor’s land ratio is a common starting point) and cost segregation split, and your own income before you talk to anyone. It will tell you roughly what is at stake and where the biggest levers are: the acquisition date, the reclass percentage, and whether the material participation test is realistic for how you actually spend your time. From there, a CPA who has filed STR loophole returns before can confirm the acquisition date rule for your contract, your state’s bonus depreciation conformity, and whether a cost segregation study is worth ordering this year versus next.
Related reading
- The STR loophole guide
- Real Estate Professional Status
- Material participation tests
- The 7-day rule: why average guest stay decides your STR tax treatment
Run your own numbers on the STR tax savings calculator, then log the hours that back them up. Try REPSLog free for 14 days on iPhone, Android or the web app.
This article and the calculator it links to are general information, not tax advice. They give an estimate for a conversation with your CPA, not a filed position.